The Roofers Fix Kit
Built for roofers and roofing contractors doing insurance claim work.
Nobody's cornered insurance-claim roofing — it's one of the most fragmented trades there is, over 24,000 firms nationally and no single one holding more than a sliver. This kit finds where the money leaks in your own work and gives you the steps and the words to close each one.
Opens secure checkout. Instant download after payment. 30 days to ask for a refund — refund policy · terms
The 7 leaks it covers
2 you can close it · 2 the other side owes it · 3 a pro decides
- Owner's own pay never checked against what the trade paysWhere to look first: Add up what you paid yourself last year from the business - wages and draws.Keep it from coming back: Put your own pay in your overhead before you price any retail job. Check your hourly against the trade figure once a year.You can close it
- Supplements for items missing from the first estimate never filed or followed upWhere to look first: Before tear-off, compare the insurer's estimate line by line with what the roof actually needs (decking, drip edge, flashing, ventilation, code items, layers, steep or high pitch).Keep it from coming back: Compare the estimate to the roof before tear-off on every job, and photograph every extra item as you find it.You can close it
- Overhead and profit cut on jobs that need general-contractor coordinationWhere to look first: On every claim, record whether the insurer's estimate includes an overhead and profit line, and whether it was held back.Keep it from coming back: Write the trades and coordination into your scope at the first inspection, before the estimate comes back.The other side owes it
- Recoverable depreciation still held by the insurer on finished jobsWhere to look first: List every insurance job you finished this year.Keep it from coming back: On every claim job, record the held-back amount and the deadline to claim it at signing. Send the completion packet the week the roof is done.The other side owes it
- Workers' comp policy not matching the crew actually workingWhere to look first: Pull your workers' comp policy and look at the class codes and the payroll it is written on.Keep it from coming back: No subcontractor starts without a current certificate on file. Review class codes and payroll with your agent before every renewal.A pro decides
- Self-employment tax and entity choice not planned for a lumpy storm seasonWhere to look first: Open a separate account for taxes and move a set share of every job payment into it the day it lands. Your CPA sets the share.Keep it from coming back: Set aside on every payment, not at tax time. Re-check the entity comparison with your CPA each year before storm season.A pro decides
- Covering or waiving the homeowner's deductible where state law bans itWhere to look first: Stop any pitch, ad or offer that covers, waives, rebates or 'absorbs' the deductible, or offers a credit or free upgrade to make up for it.Keep it from coming back: Show the deductible as the homeowner's on every invoice. Keep 'we cover your deductible' out of every ad and pitch.A pro decides
Free: one full leak from this kit
No sign-up, no email. Here is leak 1 of 7 exactly as it appears in the kit, so you can see what you get before you buy.
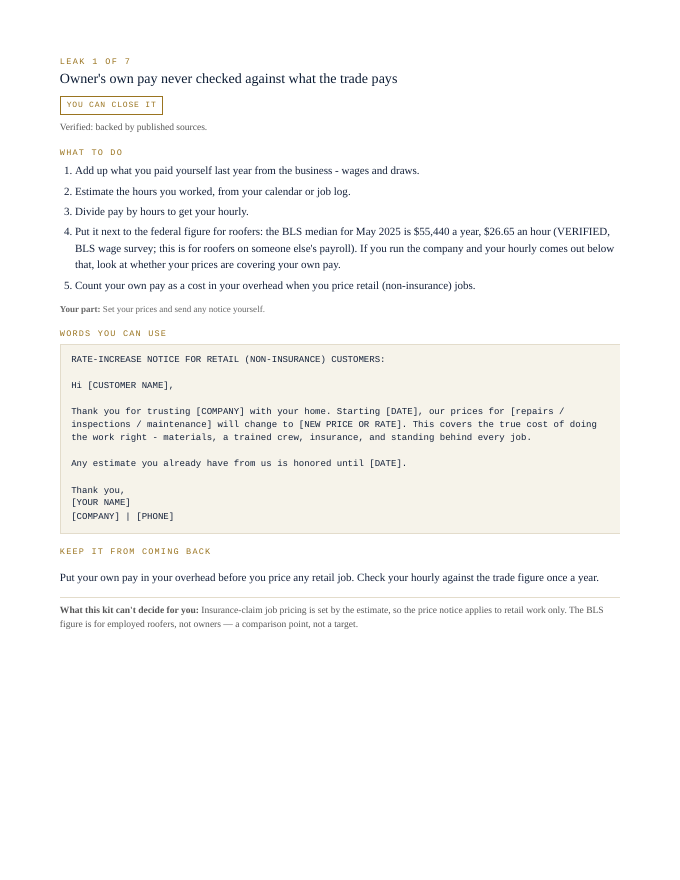
Owner's own pay never checked against what the trade pays
You can close it- Add up what you paid yourself last year from the business - wages and draws.
- Estimate the hours you worked, from your calendar or job log.
- Divide pay by hours to get your hourly.
- Put it next to the federal figure for roofers: the BLS median for May 2025 is $55,440 a year, $26.65 an hour (VERIFIED, BLS wage survey; this is for roofers on someone else's payroll). If you run the company and your hourly comes out below that, look at whether your prices are covering your own pay.
- Count your own pay as a cost in your overhead when you price retail (non-insurance) jobs.
Your part: Set your prices and send any notice yourself.
RATE-INCREASE NOTICE FOR RETAIL (NON-INSURANCE) CUSTOMERS:

Hi [CUSTOMER NAME],

Thank you for trusting [COMPANY] with your home. Starting [DATE], our prices for [repairs / inspections / maintenance] will change to [NEW PRICE OR RATE]. This covers the true cost of doing the work right - materials, a trained crew, insurance, and standing behind every job.

Any estimate you already have from us is honored until [DATE].

Thank you,
[YOUR NAME]
[COMPANY] | [PHONE]
Put your own pay in your overhead before you price any retail job. Check your hourly against the trade figure once a year.
What this kit can't decide for you: Insurance-claim job pricing is set by the estimate, so the price notice applies to retail work only. The BLS figure is for employed roofers, not owners — a comparison point, not a target.
That's 1 of 7. The other 6 come the same way in the kit: steps, words to send, a habit to keep each one closed.
Opens secure checkout. Instant download after payment. 30 days to ask for a refund — refund policy · terms
What people in this work look up
When roofers doing insurance claim work go looking for answers, they search things like “roofing insurance claims”, “roofing estimate”, “roofing business” and “roof insurance claim”. Those searches turn up forms, averages and other people's numbers. This kit starts from your own records instead: the 7 places money leaks in this work, where to look first and the words to send to close each one.
What you get for each leak
- Numbered steps to close each leak
- Your part, spelled out
- Words you can use: letters and scripts, ready to send (fill in the brackets)
- A habit that keeps each leak from coming back
- An honest line on what the kit can't decide for you
A page from the kit
Questions people ask
How do I file a roof supplement?
File and follow up for items missing from the first estimate. The kit shows how.
When do insurers owe overhead and profit?
On jobs that need general-contractor coordination. The kit shows how to support it.
How do I collect recoverable depreciation?
It's often still held by the insurer on finished jobs. The kit shows what to send.
What it can't decide for you
This kit works from your own records. It doesn't give legal, tax, licensing or financial advice, and it never tells you what to charge. Where a CPA, attorney, insurer or state board makes the call, the kit says so and gets your records ready for them.
12-page PDF · instant download after payment · Code VYR-KIT-SHINGLE-01
Opens secure checkout. Instant download after payment. 30 days to ask for a refund — refund policy · terms
Use Jobber or Housecall Pro? Run the free leak check — it reads your job export in your browser and shows the money leaks the software doesn't flag. Nothing is uploaded.